
Self Employed Mortgages In Birmingham: The Complete Freelancer & Director Guide
Running your own business in Britain’s second city comes with incredible freedom, whether you are running a boutique design agency in the Jewellery Quarter, consulting in Colmore Row, or trading trades out in Solihull. However, when it comes to securing Self Employed Mortgages In Birmingham, many sole traders and limited company directors assume the high street lenders will turn them away.
The good news? Getting a home loan when you work for yourself is not an impossible hurdle. If you are just starting your property journey or upgrading your home, speaking with …our specialized team for first time buyer mortgages in Birmingham… will give you a massive head start in securing competitive rates across the West Midlands.
In This Guide
- How Lenders Evaluate Your Self-Employed Income
- Key Documentation You Need to Prepare
- Sole Trader vs. Limited Company Director Assessment
- Self-Employed vs. Employed Mortgage Criteria
- Navigating Local Birmingham Property Nuances
- Frequently Asked Questions & Industry References
How Lenders See Your Self-Employed Income
Mainstream banks love predictable PAYE payslips. When you apply for self-employed mortgages in Birmingham, underwriters are looking for stability over time rather than a standard monthly salary figure. Generally, lenders require between 1 to 3 years of trading history.
┌─────────────────────────┐     ┌─────────────────────────┐     ┌─────────────────────────┐
│     Trading History     │ ──► │ Tax Documents / Accounts│ ──► │ Underwriter Assessment  │
│  (1 to 3+ Years Needed) │     │ (SA302s & Tax Year Ov.) │     │ (Average or Latest Yr)  │
└─────────────────────────┘     └─────────────────────────┘     └─────────────────────────┘
Your income is typically calculated using one of two methods:
- Average of the last 2 to 3 years: Ideal if your profits have fluctuated or slightly dipped.
- Most recent year’s figure: Perfect if your business in Edgbaston or Digbeth has experienced rapid recent growth, provided the lender accepts single-year assessments.
What Documents Do You Need?
Preparation is everything. Gathering these documents beforehand will streamline your application significantly:
- SA302 Summaries & Tax Year Overviews: Downloadable directly from your HMRC online account for the last 2 to 3 tax years.
- Certified Accounts: Prepared by a qualified accountant (ACCA/ICAWE) if you run a limited company.
- Bank Statements: 3 to 6 months of personal and business bank statements showing regular cash flow.
- Proof of ID & Address: Standard AML compliance docs, such as a UK driving licence or local utility bill.
Sole Trader vs. Limited Company: Comparison Table
The way high street and specialist lenders evaluate your income depends entirely on your business structure:
| Business Structure | Key Income Figure Evaluated | Best For… | Broker Tip |
| Sole Trader / Partnership | Net Profit (Share of Net Profit) | Freelancers & Tradespeople | Ensure your SA302 matches your HMRC Tax Year Overviews exactly. |
| Limited Company Director | Director’s Salary + Dividends | Established Small Businesses | Some specialist lenders assess Salary + Share of Retained Profits. |
| Contractor / Day-Rater | Day Rate $\times$ Hours/Days Worked | IT & Management Consultants | Lenders typically look for a minimum 12-month continuous contract history. |
Local Birmingham Property Considerations
From Victorian terraces in Harborne to modern city-centre apartments in the Westside, Birmingham’s property market moves quickly. Local planning policies, such as Birmingham City Council’s Article 4 directions (which restrict Houses in Multiple Occupation/HMO conversions in areas like Selly Oak or Bournville), can impact property valuations if you intend to let out parts of your home or convert space.
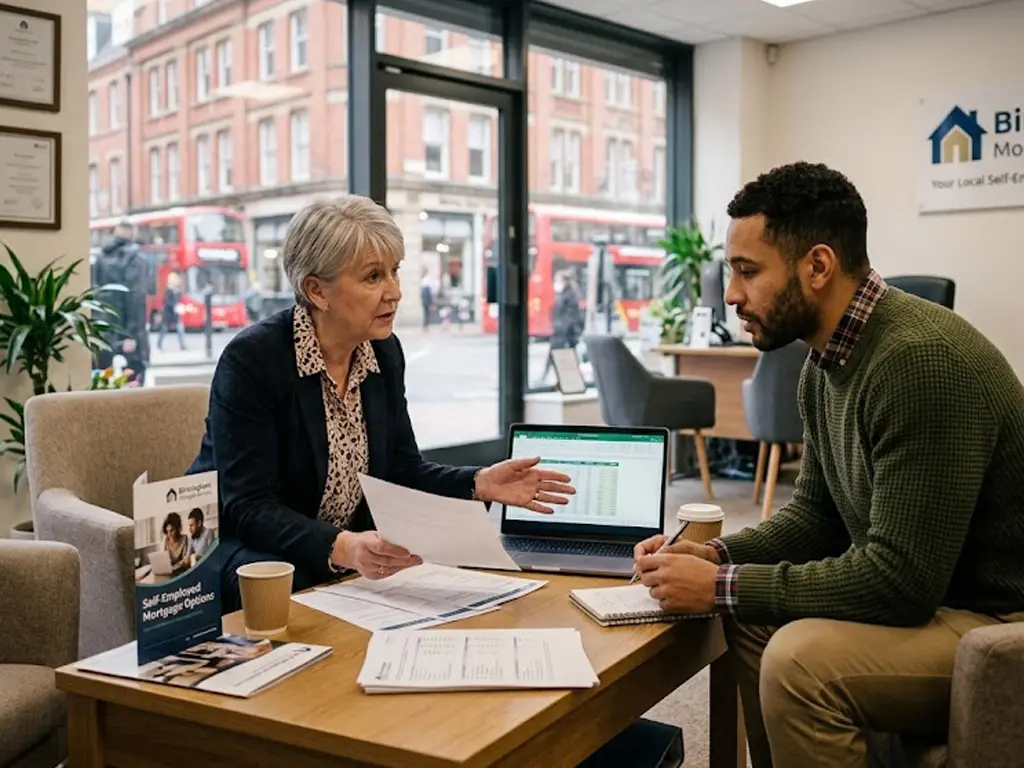
[IMAGE PLACEHOLDER: Image of our Birmingham advisers in a client meeting]
Caption: Our senior mortgage adviser meeting a client at our Birmingham office to review self-employed mortgage options.
When searching for self employed mortgages in Birmingham, working with an adviser situated in the heart of the city ensures you navigate micro-market quirks (such as specific leasehold conditions in central apartment blocks or local regeneration zones around Curzon Street) without unexpected delays.
Step-By-Step: Getting Application-Ready
- Keep Your Accounts Up To Date: Avoid changing your accounting year-end right before applying.
- Avoid Aggressive Tax Minimisation: While drawing lower dividends keeps your tax bill light, it directly reduces the amount a mortgage lender will lend you.
- Check Your Credit Profile: Use services like Experian or TransUnion to clear up any address discrepancies across the West Midlands area.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References & Further Reading
- Council of Mortgage Lenders / UK Finance Guidance: Self-Employed Lending Standards & Income Verification Framework.
- HMRC Official Portal: Understanding Your SA302 Tax Calculation and Tax Year Overviews.
- Building Societies Association (BSA): Manual Underwriting Protocols for Complex & Specialist Incomes.