
Navigating First Time Buyer Mortgages for Young People in Birmingham: A Practical Guide
uying your first home in the West Midlands can feel like trying to solve a Rubik’s cube that keeps changing shape. If you are currently hunting for First Time Buyer Mortgages for young people in Birmingham, you already know that balancing deposit requirements, property prices in Digbeth, and lender affordability checks takes more than just wishful thinking. The Birmingham market is fast-moving, driven by ongoing regeneration projects, high demand near transport hubs like Grand Central, and a growing population of young professionals.
This guide breaks down how the process works locally, what lenders actually look for, and how to position your finances to secure a key to your own front door.
In This Guide
- Understanding the Birmingham Property Landscape
- Deposit Requirements & Help to Buy Alternatives
- Key Mortgage Types Compared
- Local Rules, Council Tax & Suburb Realities
- Step-by-Step Application Roadmap
- Real-World Case Example
- Industry References
The Birmingham Reality for Young First-Time Buyers
Navigating First Time Buyer Mortgages for young people in Birmingham involves understanding a distinct regional property landscape. Unlike London, where entry-level flats often require astronomical deposits, the West Midlands offers genuine variety. However, competition remains fierce.
Areas like Erdington and Stirchley have seen significant interest due to independent high streets and direct rail links into New Street. Meanwhile, modern apartment developments in the Jewellery Quarter and Southside appeal to city-centre workers. To secure a mortgage here, you need to understand both your borrowing limits and the specific property types lenders are willing to back.
If you are just starting out, speaking with our specialized team for first time buyer mortgages in Birmingham can help clarify your maximum borrowing capacity before you begin making offers.
Deposits, Schemes, and What Lenders Expect
Most lenders expect a minimum deposit of 5% to 10% of the property’s purchase price. On a £220,000 terraced house in Kings Heath, a 5% deposit equates to £11,000, while a 10% deposit requires £22,000.
While the original government Help to Buy scheme has closed, several alternatives exist to assist young buyers:
- Deposit Unlock: Allows buyers to purchase a select new-build home with a 5% deposit via participating builders and lenders.
- Shared Ownership: Run through local housing associations (such as Midland Heart or Citizen Housing), allowing you to buy a share (e.g., 25% to 75%) of a home and pay rent on the remainder.
- Joint Borrower Sole Proprietor (JBSP): Enables family members to contribute their income toward your mortgage calculation to boost your borrowing power without adding their name to the property title deed.
Comparing Mortgage Options for First-Time Buyers
Choosing the right structure is vital for long-term affordability. Here is how the main mortgage types compare for buyers entering the West Midlands market:
| Feature | Fixed-Rate Mortgage | Tracker Mortgage | Shared Ownership Mortgage |
| Interest Rate | Remains locked for 2, 5, or 10 years | Tracks the Bank of England base rate | Fixed or variable on your purchased share |
| Budget Predictability | High; monthly payment never changes during the fix | Variable; payments rise or fall with base rate changes | Medium; monthly rent and service charges apply to the remaining share |
| Best Used For | Buyers wanting fixed monthly outgoings | Buyers expecting interest rates to drop | Buyers with smaller deposits or lower income levels |
| Early Repayment Charge | Yes, if exited during the fixed period | Often low or none (lender dependent) | Applies to the mortgaged portion |
Local Nuances: Leaseholds, Suburbs, and Council Considerations
When looking at properties in Edgbaston, Selly Oak, or Harborne, pay close attention to lease terms and local authority details.
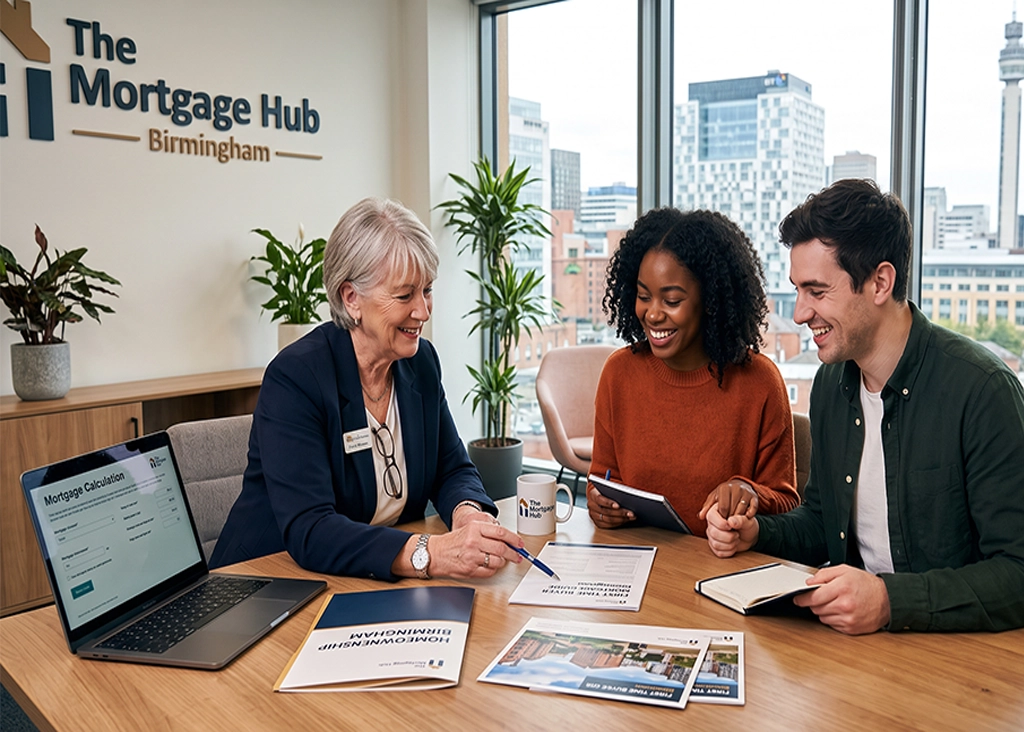
[IMAGE PLACEHOLDER: birmingham-first-time-buyer-adviser.jpg]
Caption: Our senior mortgage adviser meeting a client at our Birmingham office near Colmore Row.
When arranging First Time Buyer Mortgages for young people in Birmingham, local underwriting factors often come into play. Lenders pay close attention to city-centre leasehold details—specifically ground rent review clauses, service charge escalation rates, and short lease lengths (typically under 85 years). In suburban areas like Moseley or Perry Barr, lenders evaluate the structural build style of older Victorian terraces or non-standard construction properties common across parts of the West Midlands.
Furthermore, factor local costs into your monthly budget. Birmingham City Council sets local Council Tax bands (ranging from Band A up to Band H), which can add £120 to £250+ per month to your baseline running costs.
Step-by-Step Application Roadmap
To ensure a smooth transition from applicant to homeowner, follow this chronological sequence:
1.Check Credit Records & Clear Short-Term Debt:
Obtain full copies of your credit report from major UK credit bureaus. Settle outstanding high-interest overdrafts or credit card balances to maximize your debt-to-income score.
2.Save and Docu-Prep Deposit Funds:
Gather 3 to 6 months of bank statements, payslips, and P60s. Ensure any monetary gifts from parents are accompanied by a formal gifted deposit letter.
3.Obtain an Agreement in Principle (AIP):
Secure an AIP from a lender. This proves to Birmingham estate agents that you are a vetted buyer with confirmed borrowing backing.
4.Appoint a West Midlands Conveyancer:
Select a solicitor familiar with Birmingham City Council searches, local drainage checks, and environmental searches related to former industrial land.
Case Example: Buying in Stirchley
Consider a young professional couple earning a combined income of £52,000 per year, aiming to purchase a two-bedroom Victorian terraced property in Stirchley priced at £210,000.
- Deposit Saved: £10,500 (5%)
- Loan Amount Required: £199,500
- Mortgage Structure: 5-Year Fixed Rate at 4.2% over a 35-year term
- Estimated Monthly Mortgage Payment: ~£895/month
By securing an Agreement in Principle prior to viewing, the couple submitted a strong offer against competing buyers, meeting the lender’s affordability stress test while retaining a £3,000 cash reserve for legal fees and survey costs.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- UK Finance: Mortgage Market Trends & First-Time Buyer Analysis Report.
- Building Societies Association (BSA): Understanding First-Time Buyer Lending Practices and Affordability.
- HM Land Registry: UK House Price Index: West Midlands & Birmingham Local Authority Data.