
Step Onto the Property Ladder: 5 Percent Deposit Mortgage Advice for Birmingham First-Time Buyers
Getting a foot on the property ladder can feel challenging, but getting specialist 5 percent deposit mortgage advice Birmingham first-time buyers trust can make entering the market significantly more achievable. With high-street lenders actively competing for 95% Loan-to-Value (LTV) business across the West Midlands, securing a home with a smaller cash injection is a realistic goal for local buyers.
If you are currently renting and aiming to buy your first property in the next 6 to 12 months, consulting with …our specialist team for first time buyer mortgages in Birmingham… will clarify your exact borrowing capacity and give you a clear roadmap to application success.
In This Guide
- Understanding 95% LTV Mortgages in the Current Market
- Popular Deposit Schemes and Government Support for First-Time Buyers
- Breakdown of Upfront Costs vs. Ongoing Monthly Repayments
- Top Birmingham Neighbourhoods for 5% Deposit Buyers
- Comparison Table: Low-Deposit Mortgage Options
- Essential Steps to Prepare Your Credit File and Bank Statements
- References & Further Reading
Understanding 95% LTV Mortgages in the Current Market
A 5% deposit mortgage—technically known as a 95% Loan-to-Value (LTV) mortgage—allows you to put down just 5% of a home’s purchase price in cash while borrowing the remaining 95% from a mortgage lender. For example, on a classic £220,000 terraced property in Erdington or Stirchley, a 5% deposit requires £11,000 in upfront savings.
While low-deposit products carry slightly higher interest rates than 80% or 75% LTV options to account for increased lender risk, they dramatically reduce the time you spend stuck in the rental cycle. Choosing tailored 5 percent deposit mortgage advice Birmingham brokers provide helps ensure you balance short-term entry costs against long-term interest rate commitments.
Low-Deposit Mortgage Options Compared
+-----------------------------------------------------------------------------------+
|                        LOW-DEPOSIT SCHEMES BREAKDOWN                              |
+-----------------------+--------------------------+--------------------------------+
| Scheme / Option       | Minimum Deposit          | Key Consideration              |
+-----------------------+--------------------------+--------------------------------+
| Standard 95% LTV      | 5% of property value     | Widely available across high   |
| Mortgage              |                          | street banks and building soc. |
+-----------------------+--------------------------+--------------------------------+
| Deposit Unlock        | 5% of property value     | Restricted to participating    |
| Scheme                |                          | new-build developers           |
+-----------------------+--------------------------+--------------------------------+
| Shared Ownership      | 5% of the purchased      | Pay rent on the remaining     |
|                       | share (e.g., 25% share)  | share to a housing association |
+-----------------------+--------------------------+--------------------------------+
| Fixed £5,000 Deposit  | £5,000 flat deposit      | Subject to capped purchase     |
| Products              |                          | price limits (up to £300,000)  |
+-----------------------+--------------------------+--------------------------------+
Popular Deposit Schemes and Support Tools
Several government initiatives and private lender schemes exist to help West Midlands buyers purchase a property without waiting years to build a massive cash cushion:
- The Lifetime ISA (LISA): Save up to £4,000 per tax year toward your first home, and the UK government adds a 25% cash bonus (up to £1,000 annually).
- Deposit Unlock: A developer-backed scheme that enables first-time buyers and home movers to buy selected new-build homes with just a 5% deposit.
- Gifted Deposits: Many high-street lenders permit deposits gifted entirely by parents or close family members, provided a formal non-repayable gift letter and bank statements are supplied.
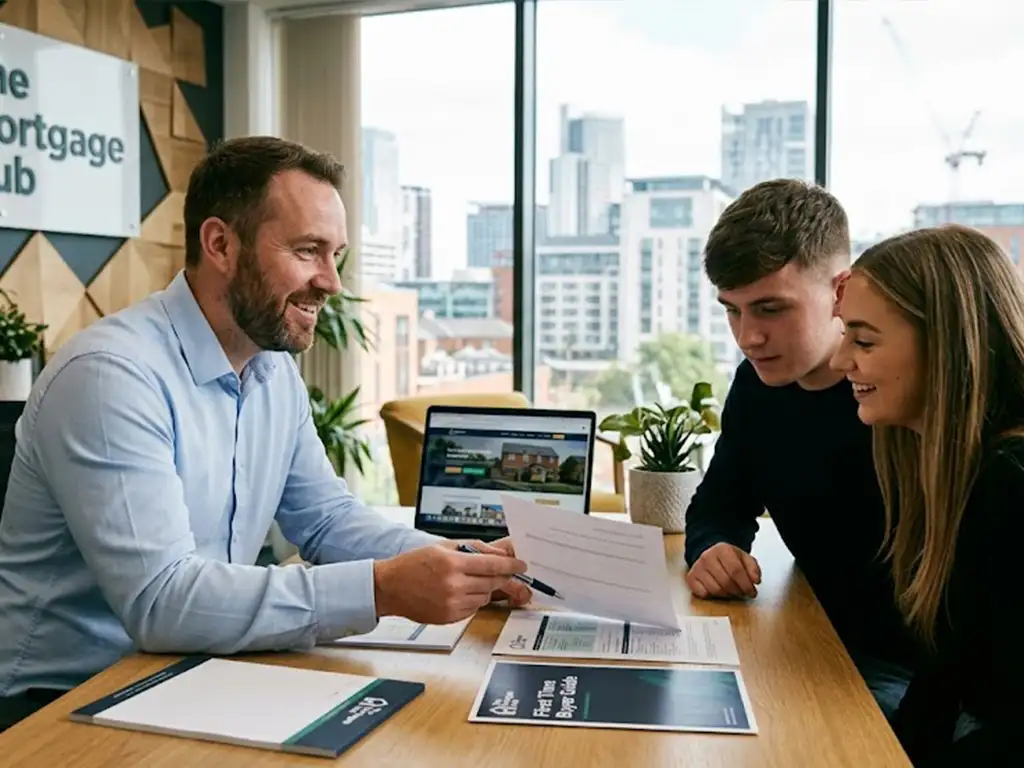
[IMAGE PLACEHOLDER: birmingham-first-time-buyer-adviser-meeting.jpg] Caption: Our senior mortgage adviser explaining 95% LTV options and deposit requirements to a first-time buyer client at our Birmingham office.
Top Birmingham Neighbourhoods for 5% Deposit Buyers
Property values vary dramatically across the West Midlands, directly impacting the monetary size of a 5% deposit. By obtaining practical 5 percent deposit mortgage advice Birmingham buyers can target key suburban pockets aligned with their target savings goal:
- Erdington & Perry Barr: Average starter homes range between £180,000 and £210,000, requiring a modest 5% deposit of £9,000 to £10,500.
- Selly Oak, Stirchley & Longbridge: Popular with young professionals due to excellent transport connections into New Street. Starter homes sit around £220,000 to £250,000 (£11,000 to £12,500 deposit).
- Jewellery Quarter & Digbeth Apartments: Modern leasehold flats offer accessible price points for single applicants, though service charges and ground rents will be added into the lender’s background affordability stress tests.
Essential Steps to Prepare Your Application
- Clean Up Your Credit File: Check Experian, Equifax, or TransUnion. Ensure you are on the electoral roll at your current Birmingham address and pay down existing credit card balances.
- Track Income and Banking Habits: Lenders scrutinize three months of bank statements. Avoid unarranged overdrafts, gambling transactions, or excessive buy-now-pay-later usage in the months before applying.
- Budget for “Hidden” Purchase Costs: Beyond your 5% deposit, hold back £2,000 to £3,500 for conveyancing fees, property surveys, and moving costs.
- Get an Agreement in Principle (AIP): Having an AIP ready proves to Birmingham estate agents that you are a verified buyer with confirmed borrowing power.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References & Further Reading
- HM Revenue & Customs (HMRC): Lifetime ISA Guidelines and First-Time Buyer Eligibility. https://www.gov.uk/lifetime-isa
- Financial Conduct Authority (FCA): Responsible Lending Conduct of Business Sourcebook (MCOB 11). https://www.fca.org.uk
- UK Finance: First-Time Buyer Lending Trends and Low-Deposit Market Analysis. https://www.ukfinance.org.uk
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.