
The Ultimate Guide to Offset Mortgages In Birmingham: How to Use Your Savings to Slash Your Mortgage Bill
For homeowners and property buyers across the West Midlands, finding clever ways to make your hard-earned money work harder has never been more critical. If you have a decent savings pot but don’t want to lock it away in a low-interest account, Offset Mortgages In Birmingham could be the financial game-changer you’re looking for. By linking your savings directly to your home loan, this product allows you to significantly reduce the amount of interest you pay, ultimately shaving years off your mortgage term.
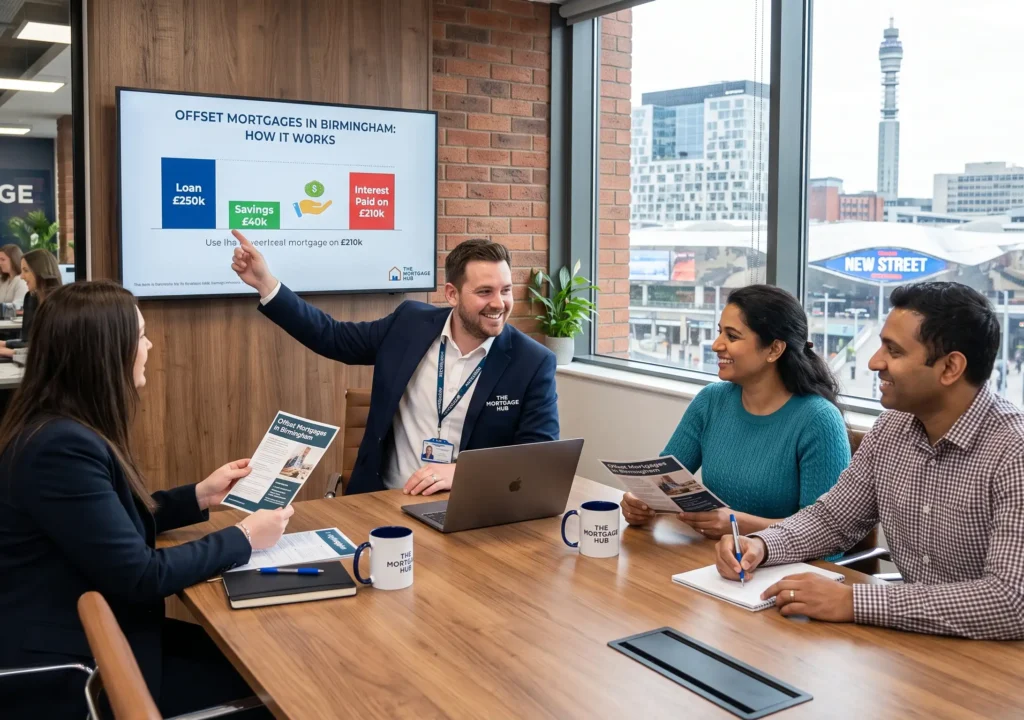
Whether you are looking to scale up to a family home in Harborne, purchase a modern apartment in the Jewellery Quarter, or speak to our specialized team for first time buyer mortgages in Birmingham about capitalising on your parental deposit, understanding how an offset structure works can save you thousands of pounds over the lifetime of your loan.
In This Guide:
- How Do Offset Mortgages Work?
- The Financial Benefits: Repayment vs. Term Reduction
- Is an Offset Mortgage Right for Birmingham Buyers?
- Comparing Offset vs. Standard Mortgages
- Local Knowledge: Navigating the West Midlands Market
- Frequently Asked Questions
How Do Offset Mortgages Work?
The concept behind an offset mortgage is beautifully simple. Instead of keeping your mortgage and your savings completely separate, a lender links them together. You don’t earn interest on your savings; instead, the balance of your savings is deducted from your outstanding mortgage balance before the monthly interest is calculated.
For example, if you have a mortgage loan of £250,000 and you hold £40,000 in a linked savings account, you will only be charged interest on £210,000.
$$£250,000 – £40,000 = £210,000$$
Your £40,000 of savings acts as a financial shield, blocking the lender from charging you interest on that specific portion of the loan. The beauty of this setup is that you still retain full access to your savings. If you need to withdraw £5,000 to renovate your property or cover an emergency, you can do so instantly—though your interest-charging mortgage balance will adjust accordingly to £215,000.
The Financial Benefits: Repayment vs. Term Reduction
When choosing how to utilise Offset Mortgages In Birmingham, lenders generally offer you two distinct paths to financial freedom:
1. Lower Monthly Payments (Payment Reduction)
Your monthly mortgage payment drops because you are only paying interest on the net amount. This frees up immediate cash flow every single month—ideal for growing families dealing with rising living costs across the West Midlands.
2. Paying Off Your Home Early (Term Reduction)
You keep your monthly payments at the standard rate as if you didn’t have savings. Because a larger portion of your monthly payment goes toward clearing the actual capital loan rather than servicing interest, you pay off the entire mortgage months or even years ahead of schedule.
The Tax Advantage: For higher-rate taxpayers, offset mortgages are incredibly tax-efficient. Because you aren’t technically “earning” interest on your savings (you are simply avoiding paying interest), there is no income tax liability on the financial benefit generated by your savings pot.
Is an Offset Mortgage Right for Birmingham Buyers?
While the benefits are clear, offset products aren’t a one-size-fits-all solution. They are uniquely suited to specific types of buyers and financial profiles:
- Self-Employed Professionals & Business Owners: If you regularly put away large pots of money to cover future tax bills (such as Payment on Account deadlines), you can keep those funds in your offset account for months, letting them reduce your mortgage interest until the day you need to pay HMRC.
- Contractors and Freelancers: If your income fluctuates, keeping a substantial emergency fund in an offset account gives you total liquidity while actively cutting your housing costs.
- Parents Providing a “Springboard”: Many lenders allow family members to link their own savings accounts to a child’s offset mortgage, helping them buy a home in areas like Edgbaston or Solihull without physically giving away the cash.
Comparing Offset vs. Standard Mortgages
To see exactly how a linked savings pot alters your financial trajectory, consider this side-by-side breakdown based on a typical West Midlands property purchase price.
| Feature | Standard Fixed-Rate Mortgage | Offset Fixed-Rate Mortgage |
| Example Loan Amount | £300,000 | £300,000 |
| Linked Savings Balance | £0 | £50,000 |
| Balance Interest is Charged On | £300,000 | £250,000 |
| Tax on Savings Interest | Subject to Personal Savings Allowance | 100% Tax-Free Benefit |
| Access to Savings Pot | Dependent on account rules | Instant access at any time |
| Best Suited For | Buyers with minimal cash reserves | Buyers with savings equal to 10%+ of loan |
Local Knowledge: Navigating the West Midlands Market
Securing Offset Mortgages In Birmingham requires a sharp understanding of the local landscape. Property dynamics vary wildly across the city. For instance, if you are targeting up-and-coming regeneration hotspots near the upcoming HS2 Curzon Street station or buying a period terrace property subject to strict local council conservation rules in Bournville, your deposit and savings strategies need to be watertight.
Lenders look closely at regional property valuations and your overall debt-to-income profile. Having a local adviser who understands the regional nuances of the West Midlands market ensures your application is directed to specialist lenders who offer competitive offset rates, rather than just the restrictive high-street options.
[IMAGE PLACEHOLDER: mortgage-hub-birmingham-offset-advisers.jpg]
Our senior mortgage adviser meeting a client at our Birmingham office to discuss flexible offset options.
As housing trends evolve across suburbs like Sutton Coldfield and Moseley, maximizing the efficiency of your cash is paramount. Working with a dedicated broker can help you navigate localized lending criteria seamlessly.
Frequently Asked Questions
Do I need a massive amount of savings for an offset mortgage?
Not necessarily, but the strategy works best if your savings equal at least 10% of the total loan value. If your savings are very low, you might get a cheaper overall rate by opting for a standard conventional mortgage instead.
Can I still move my money in and out?
Yes. Your linked savings account operates much like a standard instant-access account. If you withdraw cash, your mortgage balance subject to interest goes up the next day. If you pay money in, it drops immediately.
Are offset mortgage interest rates higher?
Sometimes, offset products carry a slightly higher initial interest rate compared to the absolute cheapest standard fixed-rate deals. However, if you hold a meaningful savings balance, the interest savings will easily outweigh that minor rate premium.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- Financial Conduct Authority (FCA) – Mortgage lending monitoring and consumer protection standards. [fca.org.uk]
- Council of Mortgage Lenders (CML) / UK Finance – Regional housing market insights and product analysis data reports. [ukfinance.org.uk]
- HM Revenue & Customs (HMRC) – Tax guidelines regarding the Personal Savings Allowance and offset structures. [gov.uk]
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.