
The Ultimate Guide to New Build Mortgages Birmingham: Navigating the West Midlands Property Market
If you are looking to secure a pristine, energy-efficient property in the heart of the West Midlands, understanding your options for New Build Mortgages Birmingham is the critical first step to turning that dream into reality. The local housing market is experiencing a massive transformation. From the soaring regeneration projects in Digbeth and the Jewellery Quarter to family-friendly developments out in Solihull and Sutton Coldfield, buying a brand-new home comes with incredible perks—but it also introduces a unique set of financing hurdles that traditional home loans don’t always cover.
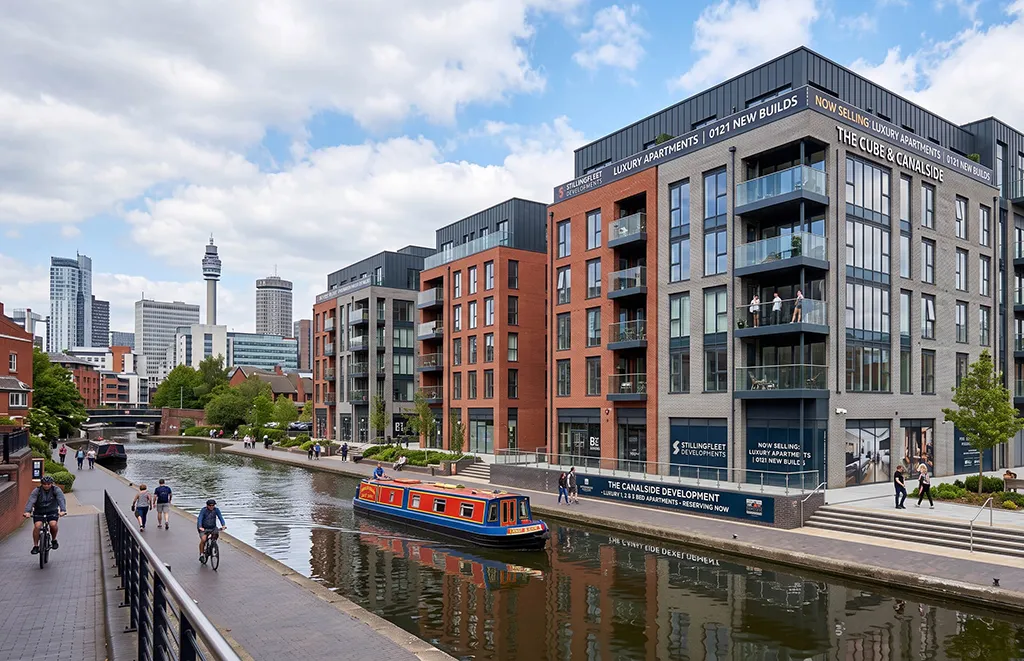
Before you put down a reservation fee on a glossy new plot, it is highly recommended to review our comprehensive guide to local property financing to see how regional market shifts might impact your borrowing power.
In This Guide
- Why New Builds in Birmingham Require Specialist Mortgages
- The Strict Timelines: The 28-Day Exchange Challenge
- Deposit Schemes and Incentives in the West Midlands
- Comparing New Build vs. Standard Residential Mortgages
- Local Considerations and Environmental Factors
- References
Why New Builds in Birmingham Require Specialist Mortgages
Securing a mortgage on a property that hasn’t been built yet—or is freshly finished—is fundamentally different from buying an existing Victorian terrace in Harborne. Lenders view new builds with a higher degree of scrutiny.
The primary reason is valuation volatility. Lenders are acutely aware of the “new car effect,” where a property can technically dip slightly in value the moment it transitions from “brand new” to “second-hand.” Because of this, when you are looking at New Build Mortgages Birmingham lenders often impose stricter Loan-to-Value (LTV) caps. While you might easily get a 95% LTV mortgage on an older home, a new build house might require a 15% deposit, and a new build city-centre apartment might demand up to 20% or 25% down.
The Strict Timelines: The 28-Day Exchange Challenge
One of the biggest shocks for first-time buyers eye-ing up developments near the Commonwealth Games legacy sites or Perry Barr is the sheer speed of the legal process.
Developers typically demand that you exchange contracts within 28 days of reserving the plot.
- The Problem: Traditional mortgage offers can take weeks to process, and if your build is delayed, your mortgage offer might expire. Most standard mortgage offers last for 3 to 6 months.
- The Solution: Specialist new build lenders offer extended offers—often up to 9 or 12 months—specifically designed to accommodate construction delays without requiring you to reapply from scratch.
Deposit Schemes and Incentives in the West Midlands
Navigating New Build Mortgages Birmingham successfully means capitalising on regional and national incentives designed to lower the barrier to entry.
Deposit Unlock
With the sunsetting of the traditional Help to Buy scheme, the industry-led Deposit Unlock scheme has stepped in. It allows buyers to secure a brand-new home with just a 5% deposit, using a mortgage backed by a developer-funded insurance policy. Major builders operating around Birmingham, such as Persimmon, Taylor Wimpey, and Barratt Homes, actively participate in this scheme.
Green Mortgages
Because Birmingham City Council is pushing hard towards its “Route to Zero” climate targets, almost all new builds in the region boast high EPC ratings (usually A or B). Embracing these energy-efficient properties unlocks “Green Mortgages.” Lenders reward you for buying an eco-friendly home by offering lower interest rates or cashback incentives upon completion.
Comparing New Build vs. Standard Residential Mortgages
To visualise how these products differ, consider the core structural contrasts:
| Feature | New Build Mortgages | Standard Residential Mortgages |
| Typical Max LTV (Houses) | 85% – 95% (Scheme dependent) | Up to 95% |
| Typical Max LTV (Flats) | 75% – 85% | Up to 95% |
| Offer Validity Period | 6 to 12 months (Extended) | 3 to 6 months |
| Incentive Eligibility | High (Green discounts, builder incentives) | Standard market rates |
| Valuation Type | Off-plan / Developer spec valuation | Standard physical survey |
Local Considerations and Environmental Factors
When applying for New Build Mortgages Birmingham specialists will look closely at local environmental and structural factors. For instance, parts of the Black Country and wider West Midlands have a rich history of mining. Lenders will require a clear mining report to ensure the ground stability of the new development.
Furthermore, if you are purchasing a high-rise apartment near New Street or the upcoming HS2 Curzon Street station, your lender will rigorously check for an EWS1 (External Wall System) form or equivalent safety certification, ensuring the building materials comply strictly with the latest UK building safety legislations. Working with a broker who understands the specific postcodes of Birmingham ensures you don’t waste time applying to lenders who turn down specific postcodes or property types.
Note to Reader: Don’t forget to add the Birmingham image location and date metadata to your media library when uploading your featured image for this article to boost local SEO signals!
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- Building Societies Association (BSA): Lending Practices for Energy Efficient and New Build Properties.
- Birmingham City Council: Our Future City Framework & Route to Zero (R2Z) Housing Action Plan.
- UK Finance: New Build Mortgage Offer Extension Protocols and Market Trends.
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.