
Navigating Mortgages in Sutton Coldfield – Birmingham: Your Ultimate Local Guide
Securing mortgages in Sutton Coldfield – Birmingham doesn’t need to feel like deciphering a cryptic puzzle while standing in the queue at New Street station. Whether you are aiming for a characterful Victorian semi near Boldmere, a modern family pad in Four Oaks, or a slick commuter base in Wylde Green, getting your home financing right in this sought-after pocket of the West Midlands is all about local know-how.
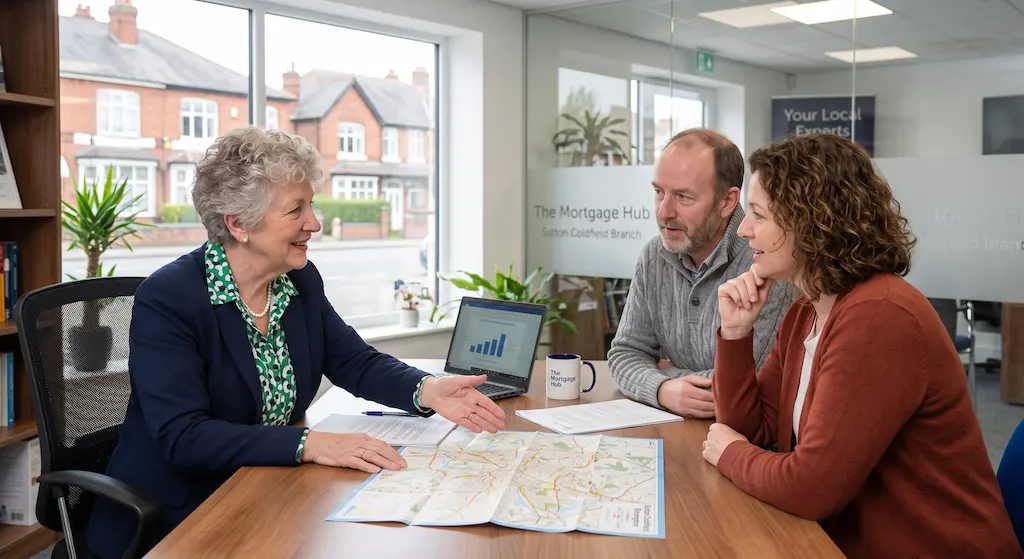
Our senior mortgage adviser meeting a client at our Birmingham office to discuss tailored mortgage options across Sutton Coldfield and the wider West Midlands.
In This Guide
- Why Sutton Coldfield Remains a West Midlands Sweet Spot
- Navigating the Local Property Terrain & Price Points
- Mortgage Types: Matching Your Property to the Right Deal
- How to Qualify: Local Council Rules, Deposit Needs & Rates
- Step-by-Step Pathway to Getting Approved
Before diving into the nuts and bolts, if you are taking your very first step onto the property ladder, speaking with [our specialized team for first time buyer mortgages in Birmingham] can help you establish your realistic borrowing limits early on.
Why Sutton Coldfield Remains a West Midlands Sweet Spot
Sitting just seven miles north of Birmingham City Centre, the Royal Town of Sutton Coldfield offers a unique blend of lush green spaces and urban convenience. With the iconic 2,400-acre Sutton Park right on the doorstep, top-tier schools such as Bishop Vesey’s Grammar, and swift rail links via the Cross-City Line, demand here consistently outpaces wider regional averages.
However, high demand means local lenders scrutinise applications carefully. Obtaining mortgages in Sutton Coldfield – Birmingham requires more than just a decent credit score; it demands an understanding of how local property nuances—such as leasehold covenants on older flats or conservation zone restrictions near Trinity Hill—impact valuation and underwriting decisions.
Navigating the Local Property Terrain & Price Points
Property values across Sutton Coldfield vary significantly depending on the specific neighborhood. Understanding these variations helps tailor your deposit strategy and lender choice.
| Suburb / Area | Average Property Price | Typical Buyer Profile | Common Mortgage Consideration |
| Four Oaks & Estate | £550,000 – £1,200,000+ | High-net-worth families, movers | Jumbo loans, complex income structures |
| Boldmere | £320,000 – £450,000 | Young professionals, second-steppers | Structural survey requirements for older stock |
| Wylde Green | £280,000 – £400,000 | Commuters, first-time buyers | Leasehold terms on converted period flats |
| Walmley | £300,000 – £425,000 | Growing families | New-build incentives & restrictive covenants |
Mortgage Types: Matching Your Property to the Right Deal
Not all loans are created equal, especially when applying for mortgages in Sutton Coldfield – Birmingham. Here is a breakdown of the main structures available:
Fixed-Rate Mortgages
Your interest rate stays locked for a set period (typically 2, 5, or 10 years). This option provides complete peace of mind and budgeting certainty, which is particularly useful if you are stretching your budget to secure a home in prime catchment areas.
Tracker & Variable Mortgages
These track the Bank of England base rate. While they can offer lower initial rates, your monthly repayments will fluctuate. They suit buyers with financial flexibility who can absorb potential rate rises.
Specialist & Offset Mortgages
If you are self-employed or run a business in Birmingham, traditional high-street stress tests can be restrictive. Offset mortgages allow you to use your savings to reduce the interest charged on your balance, maximizing tax efficiency.
Finding the ideal lender for mortgages in Sutton Coldfield – Birmingham often comes down to choosing between high-street banks on the Parade or specialist regional building societies. Local underwriters who understand the West Midlands market are far more likely to take a pragmatic view on unique property types or variable income structures.
Key Requirements: Deposits, Legislation & Local Nuances
To keep your mortgage journey smooth, keep these three essential factors in mind:
- Deposit Requirements: While 5% deposit schemes exist, having 10% to 15% saved unlocks vastly superior interest rates, saving thousands over a five-year fixed term.
- Birmingham City Council Rules: Be aware of local planning restrictions, particularly regarding Houses in Multiple Occupation (HMOs) or extensions in conservation zones, as lenders check these during conveyancing.
- Leasehold Standards: If buying a flat near Sutton station, lenders generally require at least 80–85 years remaining on the lease before granting standard rates.
Step-by-Step Pathway to Getting Approved
- Calculate True Affordability: Factor in Stamp Duty, survey costs, and solicitor fees alongside your deposit.
- Secure an Agreement in Principle (AIP): Having an AIP ready gives estate agents in Sutton Coldfield confidence that you are a serious buyer.
- Gather Documentation: Prepare 3 months of payslips, 3 months of bank statements, proof of ID, and tax returns (if self-employed).
- Submit Full Application: Your broker submits your details and instructs the property valuation.
- Offer & Conveyancing: Once the lender issues the formal offer, your solicitor manages legal searches through Birmingham City Council before exchange.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- UK Finance: Mortgage Lending Trends & Regional Performance Reports (ukfinance.org.uk)
- HM Land Registry: UK House Price Index: West Midlands & Birmingham Data (gov.uk/government/organisations/land-registry)
- Council of Mortgage Lenders Archive / Building Societies Association: Underwriting Standards for Suburban Properties (bsa.org.uk)