
Navigating Self Employed Mortgages for Birmingham Sole Traders: The Complete Guide
Securing self employed mortgages for Birmingham sole traders doesn’t have to be an uphill battle against rigid High Street underwriting algorithms. Whether you run a bustling trade business out of Digbeth, manage a digital consultancy in the Jewellery Quarter, or operate a flourishing local service across Solihull and Edgbaston, operating as a sole trader brings unique financial flexibility—alongside specific mortgage hurdles.
If you are looking to purchase your first home, trade up, or remortgage, getting the right advice early makes all the difference. You can speak directly with our specialized team for self employed mortgages in Birmingham to assess your borrowing capacity based on your actual SA302 calculations rather than generic online estimates.
In This Guide
- How Lenders Evaluate Sole Trader Income
- Net Profit vs. Total Turnover: What Lenders Actually Look At
- High Street Banks vs. Specialist West Midlands Lenders
- Step-by-Step Preparation Checklist for Sole Traders
- Local Market Factors Across Birmingham & the West Midlands
- Key References & Resources
Understanding Income Assessment for Sole Traders
When you apply for a home loan as a sole trader, mortgage underwriters do not assess your business in the same way they do limited company directors. You don’t have a salary or dividend split; instead, lenders look directly at your net profit (your total turnover minus allowable business expenses).
Gross Business Income (Turnover)
  − Allowable Business Expenses
  = Net Taxable Profit (The figure lenders multiply for your loan amount)
Most mainstream lenders calculate your maximum borrowing amount by averaging your net profit over the last two to three trading years. Typically, they will apply an income multiple of 4.5x to 5.5x to this average figure.
+------------------------------------+-----------------------------------+-----------------------------------+
| Trading History                    | Standard High Street Assessment   | Specialist Lender Assessment     |
+------------------------------------+-----------------------------------+-----------------------------------+
| 3+ Years Accounts                  | Averages last 2–3 years net profit| Uses most recent year if growing  |
| 2 Years Accounts                   | Averages 2 years net profit       | Uses most recent year's net profit|
| 1 Year Accounts (SA302 available)  | Usually Decline / Auto-Reject     | Accepts 1 year net profit         |
+------------------------------------+-----------------------------------+-----------------------------------+
The Pitfall of Tax Minimisation
As a sole trader working with a local Birmingham accountant, your primary strategy at tax year-end is often to legally minimise your taxable income by writing off legitimate business expenses—such as tool wear-and-tear, vehicle mileage, or home office costs.
While this lowers your Self Assessment tax bill, it directly reduces your net profit figure on paper. When applying for self employed mortgages for Birmingham sole traders, a lower net profit translates directly to lower maximum borrowing power. Balancing tax efficiency with your future home ownership ambitions requires proactive planning at least 12 to 24 months before submitting a formal application.
High Street vs. Specialist West Midlands Lenders
Not all mortgage lenders treat self-employed income the same way. The UK mortgage landscape generally splits into two categories for sole traders:
1. High Street Lenders (Barclays, HSBC, NatWest)
- Pros: Highly competitive interest rates, low product fees.
- Cons: Rigid automated credit scoring; strictly require 2–3 years of SA302s; always average fluctuating profits (even if year three was your best year yet).
2. Specialist & Regional Lenders
- Pros: Manual underwriting; willing to consider just 1 year of trading accounts; will assess the latest year’s profits if business trajectory shows clear upward growth.
- Cons: May require slightly higher initial deposits (typically 10%–15% minimum).
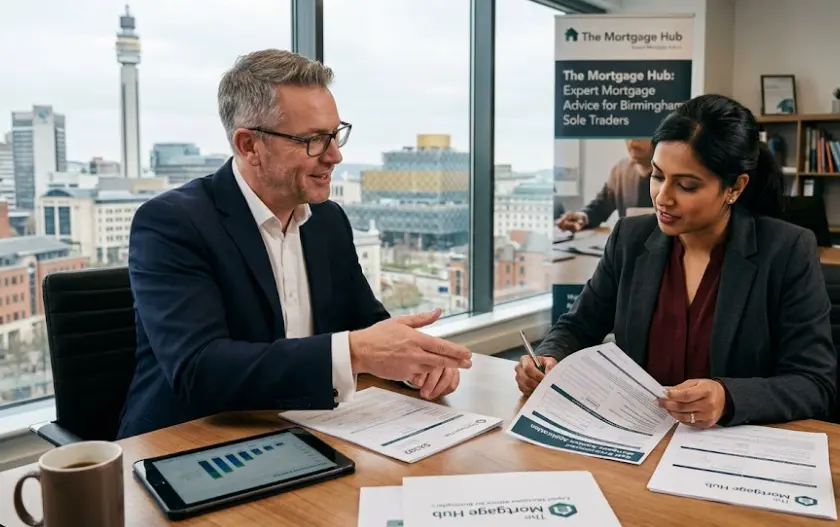
Our senior mortgage adviser meeting a client at our Birmingham office to discuss self-employed mortgage options.
When arranging self employed mortgages for Birmingham sole traders, accessing regional building societies across the West Midlands—such as Tipton & Coseley, West Bromwich Building Society, or Leek Building Society—can often unlock options that nationwide High Street brands automatically decline. Local underwriters understand the economic vitality of Birmingham’s commercial hubs, from industrial trades in Smethwick and Aston to tech startups around Eastside.
Step-by-Step Mortgage Checklist for Sole Traders
To streamline your mortgage journey, assemble your financial paperwork before viewing properties across Sutton Coldfield, Harborne, or Stirchley.
- Obtain Tax Calculations (SA302s) & Tax Year Overviews: Request these directly from your HMRC online account or ask your accountant. You will need these documents for the most recent 2 to 3 tax years. Ensure the Tax Year Overviews match the figures stated on your SA302s exactly.
- Compile 6 Months of Bank Statements: Underwriters review business and personal bank accounts to verify that income declared on tax returns aligns with ongoing cash flow. Ensure business expenses are kept separate from personal accounts.
- Check Your Credit Profile: Pull your multi-agency credit report via CheckMyFile or Experian. Resolve any electoral roll mismatches or minor late payment markers early.
- Prepare Proof of Deposit: Lenders enforce strict Anti-Money Laundering (AML) checks. Be ready to evidence where your deposit originated—whether accumulated through saved trading profits or a family gift.
Local Market Realities: Buying in Birmingham as a Sole Trader
The Birmingham property market presents distinct micro-markets depending on where you are looking to purchase:
- First-Time Buyer Hotspots (Erdington, Kings Heath, Longbridge): Lower average purchase prices mean smaller overall deposits, making 1-year accounts applications viable for sole traders entering the ladder.
- Family Homes (Harborne, Edgbaston, Moseley): Higher property valuations require stronger net profit figures. If your profits spiked significantly in the latest tax year due to major local contract wins, finding a lender who accepts the most recent year’s figures rather than a 3-year average is essential.
Working alongside knowledgeable advisers who specialize in self employed mortgages for Birmingham sole traders ensures your application is pitched to an underwriter who values your trading performance and understands the West Midlands property market.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- HM Revenue & Customs (HMRC): Get a Tax Calculation (SA302) and Tax Year Overview. https://www.gov.uk/sa302-tax-calculation
- Financial Conduct Authority (FCA): Mortgage Conduct of Business (MCOB) Sourcebook – Responsible Lending Rules. https://www.handbook.fca.org.uk/handbook/MCOB/
- UK Finance: Mortgage Lending Trends and Self-Employed Borrower Insights. https://www.ukfinance.org.uk/
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.