
Bank of England Rate Decisions: How Birmingham Homeowners Can Protect Their Repayments
Navigating fluctuating interest rates can feel daunting, but securing tailored base rate mortgage advice Birmingham homeowners can rely on is the single most effective way to protect your monthly household budget. With the Bank of England Monetary Policy Committee (MPC) maintaining the base rate at 3.75%, many local buyers and existing homeowners across the West Midlands are wondering whether they should lock in a fixed deal now or wait for potential cuts later in the year.
If your current fixed deal is expiring within the next 6 to 12 months, speaking with …our experienced team providing specialist remortgage options in Birmingham… allows you to reserve a competitive rate up to six months before your existing deal finishes, completely risk-free.
In This Guide
- How the Bank of England Base Rate Directs Local Mortgage Products
- Fixed vs. Tracker Mortgages in the Current Birmingham Market
- Timing Your Remortgage: The 6-Month Lock-In Strategy
- Hyper-Local Property Trends Across Birmingham Suburbs
- Comparison Table: Rate Options Breakdown
- Practical Steps to Take Before the Next MPC Announcement
- References & Further Reading
How the Bank of England Base Rate Directs Local Mortgage Products
When the Monetary Policy Committee sets the benchmark UK interest rate, commercial lenders adjust their wholesale borrowing costs almost immediately. For homeowners in popular Birmingham suburbs—from Victorian terraces in Harborne and Moseley to modern suburban developments in Solihull and Sutton Coldfield—the impact varies depending on the type of mortgage deal you hold.
- Tracker Mortgages: These directly follow the Bank of England base rate. When the rate holds or drops, your monthly payment responds accordingly without delay.
- Standard Variable Rates (SVR): Lenders set their own SVRs. While they tend to move in tandem with base rate adjustments, banks are not legally obligated to pass on full reductions.
- Fixed-Rate Mortgages: These are priced based on long-term swap rates rather than the immediate base rate alone. Expectations of future economic policy are already priced into today’s 2-year, 5-year, and 10-year fixed deals.
Understanding these mechanics is crucial when seeking reliable base rate mortgage advice Birmingham property owners can use to make proactive, calculated choices rather than reactive ones.
Fixed vs. Tracker Mortgages in Current Market Conditions
Choosing between a fixed-rate safety net and a variable tracker requires balancing risk tolerance against immediate savings.
+-----------------------------------------------------------------------------------+
|                        MORTGAGE PRODUCT COMPARISON                                |
+-----------------------+--------------------------+--------------------------------+
| Product Type          | Key Benefit              | Ideal For                      |
+-----------------------+--------------------------+--------------------------------+
| 2-Year Fixed          | Short-term certainty     | Borrowers expecting lower      |
|                       | without long commitment  | rates in 24 months             |
+-----------------------+--------------------------+--------------------------------+
| 5-Year Fixed          | Complete budget stability| Families seeking long-term     |
|                       | and protection           | predictable monthly outgoings  |
+-----------------------+--------------------------+--------------------------------+
| Base-Rate Tracker     | Immediate savings if     | Homeowners comfortable with    |
|                       | central rates drop       | payment fluctuations           |
+-----------------------+--------------------------+--------------------------------+
While tracker deals offer lower initial headline rates in falling markets, fixed deals eliminate financial surprises—an vital consideration for households managing urban living costs across the West Midlands.
The 6-Month Lock-In Strategy: Proactive Rate Management
One of the most valuable aspects of professional base rate mortgage advice Birmingham advisers provide is guiding clients through product transfers and advance rate reservations.
Most UK lenders allow borrowers to secure a new fixed rate up to 180 days before their existing mortgage deal expires.
Expert Tip: Reserving a rate six months in advance acts as a free insurance policy. If mortgage rates rise prior to your renewal date, your lower rate is locked in. If rates fall, you can switch to the cheaper rate before your new term officially starts.
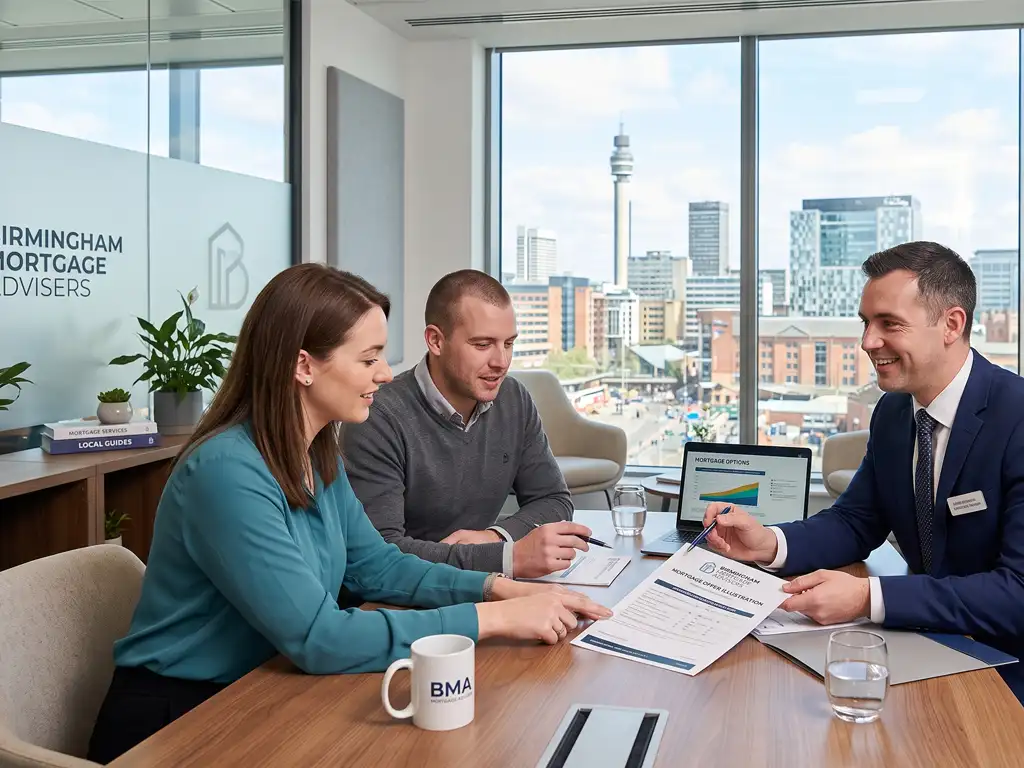
[IMAGE PLACEHOLDER: birmingham-mortgage-advisers-office-meeting.jpg] Caption: Our senior mortgage advisers reviewing fixed rate options and base rate trends with clients at our Birmingham office.
Hyper-Local Property Trends Across Birmingham Suburbs
Mortgage decisions do not happen in a vacuum—they are closely tied to local property valuations across the West Midlands. Equity levels heavily influence the Loan-to-Value (LTV) band you fall into, which directly dictates the interest rates available to you.
- Jewellery Quarter & Digbeth: High concentration of leasehold apartments where service charges and cladding compliance combine with interest rates to impact overall affordability.
- Edgbaston & Harborne: Strong property value retention provides substantial equity buffers, often unlocking tier-one LTV rates (sub-60% LTV).
- Sutton Coldfield & Solihull: Larger family homes where even a 0.25% shift in interest rates translates to significant monthly monetary differences.
By obtaining structured base rate mortgage advice Birmingham homeowners can accurately re-evaluate their property’s current market value to jump into lower LTV tiers, securing significantly discounted pricing.
Practical Steps to Take Ahead of the Next Rate Announcement
- Check Your Expiry Date: Locate your current mortgage offer document to confirm exactly when your benefit period ends.
- Review Your Current LTV: Obtain an up-to-date valuation estimate for your Birmingham property to calculate your remaining loan percentage.
- Audit Monthly Outgoings: Lenders assess overall debt-to-income ratios under strict FCA affordability frameworks.
- Speak with an Independent Broker: Access whole-of-market options rather than restricting yourself to your current lender’s retention rates.
Ready to Secure Your Mortgage in Birmingham?
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References & Further Reading
- Bank of England Monetary Policy Committee: Monetary Policy Summary and Minutes (June 2026 Announcement). https://www.bankofengland.co.uk
- UK Finance: Mortgage Market Trends and Lending Analysis Report. https://www.ukfinance.org.uk
- Financial Conduct Authority (FCA): Mortgage Conduct of Business (MCOB) Guidelines on Responsible Lending. https://www.fca.org.uk
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.