
The Smart Guide to Low Deposit Mortgages Birmingham: How to Get on the West Midlands Property Ladder
For many aspiring homeowners across the West Midlands, saving a massive 15% or 20% deposit can feel like an impossible mountain to climb, which is why finding the right Low Deposit Mortgages Birmingham options has become an absolute game-changer. With property prices fluctuating and the cost of living still biting, putting down a smaller sum—typically between 5% and 10%—is often the quickest, most practical route into homeownership.
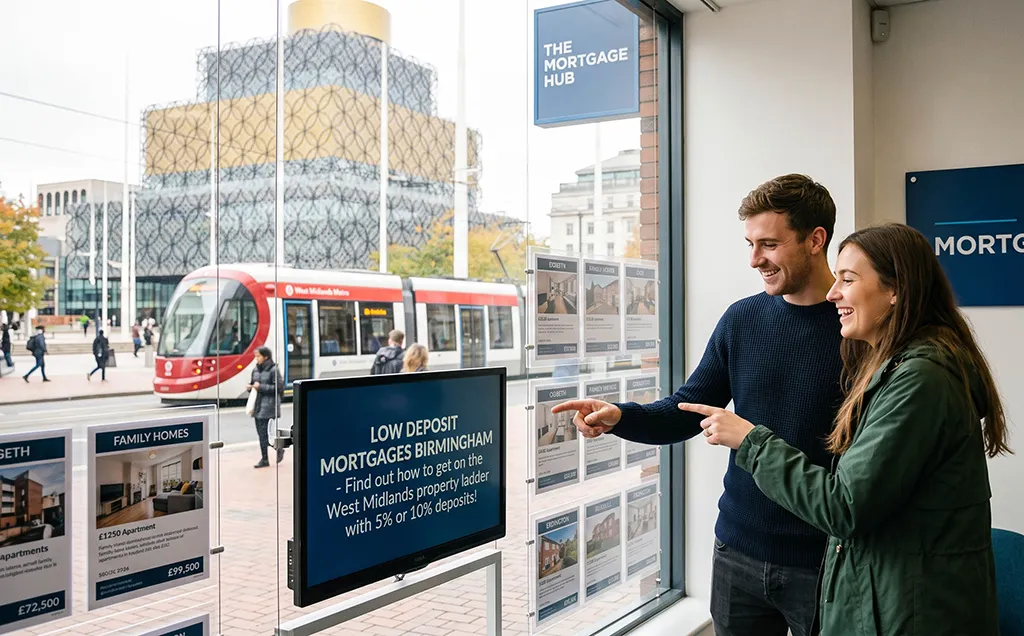
Whether you are eyeing up a trendy apartment in Digbeth, a family semi-detached in Solihull, or a regeneration plot in Erdington, navigating the local market requires an expert approach. Before diving into the specifics, it is wise to understand your foundational options by checking out our comprehensive guide to West Midlands mortgage advice.
In This Guide
- The Reality of the Birmingham Property Market
- Types of Low Deposit Mortgages Available
- Key Local Schemes and Council Initiatives
- Comparing Low Deposit Mortgage Options
- Step-by-Step Action Plan to Qualify
- References
The Reality of the Birmingham Property Market
Birmingham is currently one of the most dynamic property hubs in the UK. Driven by massive infrastructure projects like the ongoing HS2 developments, the Big City Plan, and the rejuvenation of areas like the Jewellery Quarter and Smithfield, prices have seen steady long-term growth.
However, this popularity means first-time buyers face stiff competition. While average property prices in the West Midlands remain significantly more affordable than in London and the South East, saving a £20,000+ deposit while simultaneously paying city-centre rents is a tough ask. This reality has driven a surge in demand for Low Deposit Mortgages Birmingham schemes, allowing buyers to capitalise on the market sooner rather than later.
Types of Low Deposit Mortgages Available
If you only have a 5% or 10% deposit saved, you are not locked out of the market. Lenders have become increasingly innovative in how they assess affordability.
1. The 95% LTV Mortgage
Loan-to-Value (LTV) is the percentage of the property value you borrow versus what you pay upfront. A 95% LTV mortgage means you provide a 5% deposit. Many high-street lenders offer these, backed in part by historical government guarantee structures, making them a highly accessible route for standard residential purchases.
2. Shared Ownership
Regulated heavily by local housing associations and Birmingham City Council, Shared Ownership allows you to buy a share of a property (usually between 10% and 75%) and pay rent on the remaining share. Because you are only buying a piece of the property, your 5% or 10% deposit is calculated based on the value of your share, not the total property price. This drastically lowers the financial barrier to entry.
3. Guarantor and “Springboard” Mortgages
If your savings are falling short but you have family members willing to assist, a guarantor or family springboard mortgage is an excellent route. Instead of gifting you cash, family members can place a deposit (typically 10%) into a locked savings account with the lender as security, allowing you to secure a 0% or 5% deposit mortgage.
Key Local Schemes and Council Initiatives
When searching for Low Deposit Mortgages Birmingham deals, it is vital to look at hyper-local initiatives. The West Midlands Combined Authority (WMCA) and Birmingham City Council frequently collaborate with developers to ensure affordable housing quotas are met in major new-build developments.
- WMCA Affordable Housing Scheme: The WMCA applies its own definition of affordability, aiming to ensure new homes built across Greater Birmingham are accessible to local workers. This often means specific allocations of discounted market sale homes or prioritised Shared Ownership units in areas like Perry Barr and Smethwick.
- Section 106 Agreements: Keep an eye out for new build sites across the city. Developers are frequently bound by Section 106 agreements, requiring them to offer a percentage of units to local first-time buyers at a discounted rate, making a low-deposit mortgage stretch much further.
Comparing Low Deposit Mortgage Options
To give you a clearer picture of how your upfront costs and monthly commitments might look, here is a breakdown of the standard pathways for a property valued at £200,000.
| Mortgage Pathway | Required Deposit % | Example Deposit Amount | Pros | Cons |
| Standard 95% LTV | 5% | £10,000 | 100% property ownership; no rent to pay. | Higher interest rates; stricter credit checks. |
| Shared Ownership (50% Share) | 5% (of the share) | £5,000 | Very low entry cost; accessible with lower income. | You must pay rent on the unowned 50%; staircasing fees apply. |
| Standard 90% LTV | 10% | £20,000 | Access to significantly better interest rates. | Takes longer to save the initial lump sum. |
Step-by-Step Action Plan to Qualify
Securing a mortgage with a smaller deposit means lenders will look at the rest of your application under a microscope. To maximise your chances of approval for Low Deposit Mortgages Birmingham products, follow this checklist:
- Optimise Your Credit Report: Download your file via Experian or Equifax. Ensure you are registered on the electoral roll at your current Birmingham address and clear any outstanding payday loans or credit card balances.
- Prove Sustainable Income: Lenders will scrutinise your bank statements. Avoid large, unexplained cash withdrawals or gambling stints in the 3–6 months leading up to your application.
- Account for Fee Outlays: Remember that your deposit isn’t your only cost. You will need to budget for stamp duty (if applicable), survey fees, and local West Midlands conveyancing solicitors.
- Speak to a Regional Broker: Local knowledge matters. A broker rooted in the Midlands will know which niche lenders are currently look favourably on specific property types in Birmingham, such as high-rise city apartments or non-standard construction builds.
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- Official Birmingham City Council Housing Strategy: birmingham.gov.uk
- West Midlands Combined Authority (WMCA) Affordable Housing Framework: wmca.org.uk
- Financial Conduct Authority (FCA) Mortgage Lending Statistics: fca.org.uk
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.