
5 Brilliant Ways Government Scheme Mortgages in Birmingham Fast-Track Your Home Ownership
Navigating the property ladder in the West Midlands can feel like an uphill struggle, but finding the right Government Scheme Mortgages in Birmingham can completely transform your homeownership journey. With rising living costs making it harder to accumulate a traditional 20% deposit while renting in vibrant areas like Digbeth or the Jewellery Quarter, government-backed initiatives are stepping in to bridge the affordability gap.
Before diving into specific local criteria, it is wise to review our foundational first-time buyer mortgage guide to grasp core lending principles and understand how much you might be eligible to borrow.
In This Guide
- The Evolving West Midlands Property Landscape
- Key Government Mortgage Schemes Available Internationally and Locally
- Comparing Your Birmingham Mortgage Options
- Navigating Local Council Eligibility Criteria
- Practical Steps to Securing Your Mortgage
- Industry References
The Evolving West Midlands Property Landscape
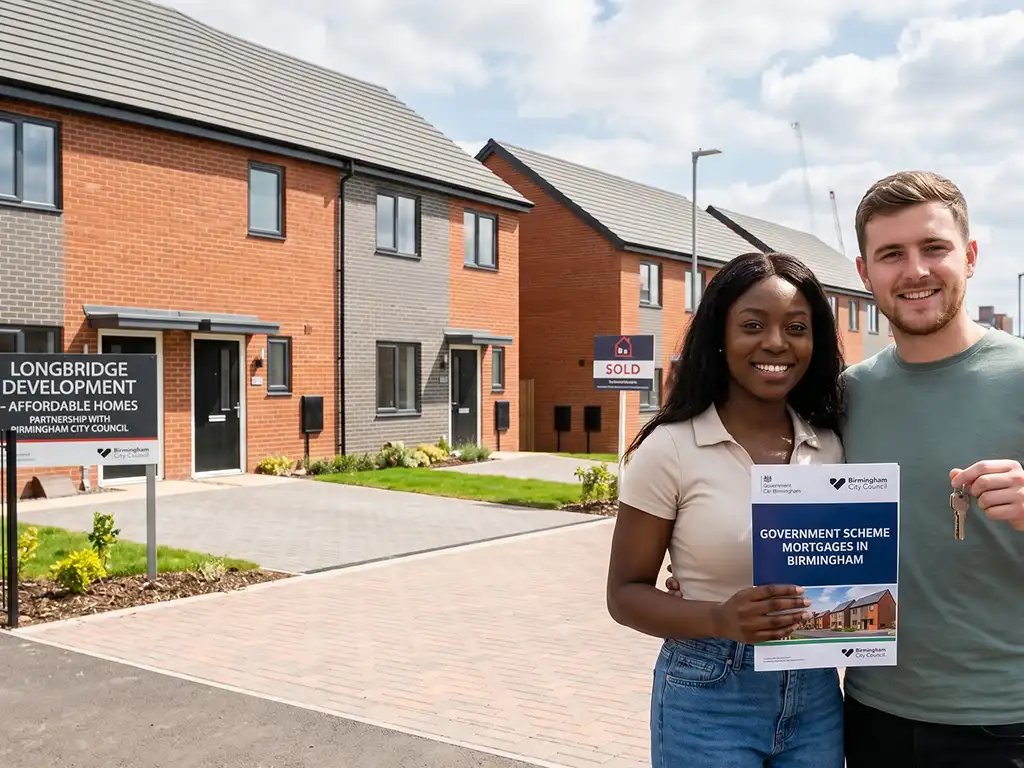
The Birmingham housing market has experienced significant transformation. Regeneration projects across the city—from the expansion of Paradise Birmingham to residential hubs in Longbridge—have driven up property values. This growth is fantastic for the local economy, but it introduces substantial hurdles for buyers trying to keep pace with deposit requirements.
To counter this, the West Midlands Combined Authority (WMCA) has taken a unique approach by redefining what “affordable housing” actually means. Unlike the traditional national definition, which simply prices affordable homes at 80% of market value, the WMCA framework links affordability directly to local earnings. This policy targets a reality where housing costs (whether rent or mortgage repayments) do not exceed 35% of an average local household income. This localized focus makes finding a suitable mortgage structure more attainable for those working within the city limits.
Key Government Mortgage Schemes
When evaluating the various Government Scheme Mortgages in Birmingham, the First Homes scheme stands out as an exceptional option for local buyers. However, it is just one of several frameworks designed to bring homeownership within reach.
1. The First Homes Scheme
This initiative offers a substantial discount of at least 30% (and up to 50% in specific localized developments) on the market value of brand-new properties.
- The Local Impact: In developments like Chapmans Yard or South Central in central Birmingham, a flat valued at £220,000 can be marketed to eligible buyers at £154,000.
- The Catch: The discount locks into the property permanently. When you eventually choose to sell, the same percentage discount must be passed on to the next qualifying local buyer.
2. Shared Ownership
If saving for a full mortgage is out of reach, Shared Ownership allows you to purchase a share of a property (typically between 10% and 75%) and pay a subsidised rent on the remaining portion to a housing association. Over time, you can engage in “staircasing”—buying further shares as your financial position improves until you own the property outright. This is highly popular in developing suburbs like Erdington, Shirley, and parts of Solihull.
3. The Mortgage Guarantee Scheme
For buyers who can afford monthly repayments but lack a massive capital lump sum, this scheme encourages commercial lenders to offer 95% Loan-to-Value (LTV) mortgages. The government provides a financial guarantee to the lender, lowering their risk and opening access to competitive fixed-rate deals with just a 5% deposit.
Comparing Your Birmingham Mortgage Options
| Scheme Name | Typical Discount / Share Available | Minimum Deposit Required | Key Local Eligibility Requirement |
| First Homes Scheme | 30% to 50% market discount | 5% of discounted price | Max £80,000 household income & clear local connection |
| Shared Ownership | 10% to 75% equity shares | 5% to 10% of the shared portion | Household income under £80,000; restricted to approved housing association sites |
| Mortgage Guarantee Scheme | 100% ownership (95% LTV mortgage) | 5% of full market value | Standard credit checks apply; maximum property value of £600,000 |
Navigating Local Council Eligibility Criteria
Securing one of the Government Scheme Mortgages in Birmingham requires a clear understanding of both national guidelines and specific regional variations. Birmingham City Council implements strict guardrails to ensure these schemes benefit the local community rather than speculative investors.
To qualify for a First Homes discount within the city boundaries, applicants generally must meet the following criteria:
- First-Time Buyer Status: You, and anyone you are purchasing with, must have never owned a residential property anywhere else in the world.
- Income Caps: Your gross combined household income from the previous tax year cannot exceed £80,000.
- Local Connection Priority: The council actively prioritises key workers (such as NHS staff at the Queen Elizabeth Hospital, emergency services personnel, and local educators) or individuals who have lived or worked within Birmingham for a defined consecutive period.
The application workflow is deeply integrated with the local authority. Once you identify an eligible plot through a participating developer, you must submit a formal application. If approved, Birmingham City Council will issue an Authority to Proceed and an Eligibility Certificate, which your conveyancing solicitor will require before exchanging contracts.
Practical Steps to Securing Your Mortgage
If you are ready to transition from renting to capitalising on your own property, exploring Government Scheme Mortgages in Birmingham with an independent expert is the most effective path forward. Lenders evaluate scheme-backed applications with distinct criteria, assessing both your standard borrowing capacity and the specific terms of the government incentive.
- Obtain an Agreement in Principle (AIP): Before falling in love with a property in Edgbaston or Sutton Coldfield, establish exactly what a lender will offer based on your income and credit profile.
- Gather Local Proofs: Prepare your employment contracts, P60s, and evidence of your local residency or key worker status to satisfy council checks smoothly.
- Engage a Specialised Broker: Working with a team that understands the nuances of the West Midlands housing landscape ensures you target the right products, reducing the risk of a declined application.
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- Birmingham City Council: Affordable Housing Policy and First Homes Implementation Guidance
- West Midlands Combined Authority (WMCA): Homes for the Future Strategy & The Localised Affordability Framework
- GOV.UK: First Homes Scheme: First-Time Buyer’s Guide and National Eligibility Framework (Revised Edition)
Have questions about your next steps? Head back to The Mortgage Hub Blog List to explore our full library of homebuying guides, rate updates, and local advice.” to each blog. to complete all the spokes.