
The Smart Guide to Securing New Build Mortgages In Birmingham
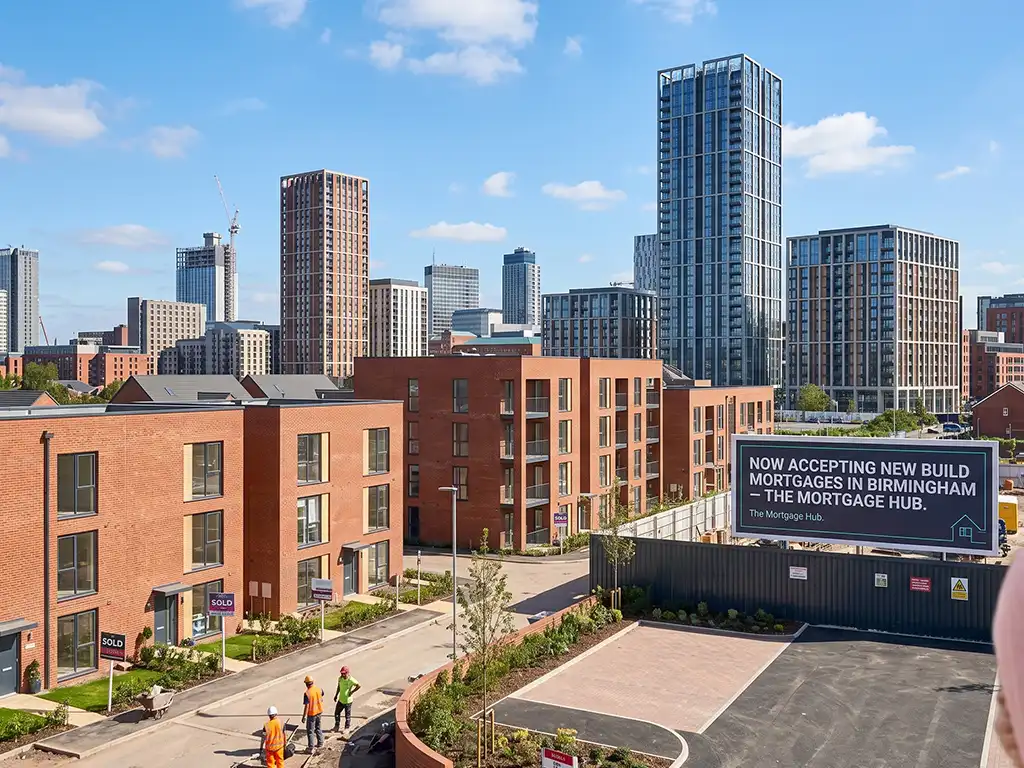
The Second City is experiencing an unprecedented construction boom. From the glass towers reshaping the city centre skyline to the sprawling suburban family developments in the West Midlands, the regional housing market is evolving at pace. Navigating this landscape requires specialist local knowledge, which is why securing New Build Mortgages In Birmingham requires a tailored approach distinct from buying an established property. Whether you are looking to step onto the property ladder in Digbeth, buy a family home in Solihull, or upgrade your portfolio, understanding how lenders view newly constructed properties in the local authority framework is essential to unlocking the best rates.
To help you navigate this fast-moving market, you can explore our comprehensive analysis or speak directly with an expert via our foundational new build financing framework.
In This Guide
- The Reality of New Build Financing in the West Midlands
- Birmingham’s Strategic Development Zones
- Crucial Lending Pitfalls: The Offer Validity Trap
- Local Regulations, Warranty Frameworks, and Building Safety
- Comparison: New Build Mortgages vs Standard Residential Mortgages
- References
The Reality of New Build Financing in the West Midlands
Securing a mortgage on a property that has never been lived in introduces unique criteria from underwriting teams. Lenders often view new builds with a degree of caution due to what the industry terms the “new build premium”—the risk that a property might experience a slight, temporary drop in value immediately after the first sale, similar to driving a brand-new car off a dealership forecourt.
Because of this, if you are looking for New Build Mortgages In Birmingham, you will find that maximum Loan-to-Value (LTV) limits are tighter. While you can easily secure a 95% LTV mortgage on an older Victorian terrace in Harborne, lenders often cap new build flats at 80% to 85% LTV, and new build houses at 85% to 90% LTV.
Furthermore, incentives offered by developers to seal the deal—such as paid stamp duty, cashback, or premium flooring packages—must be carefully vetted. Most high-street lenders dictate that if the total value of these incentives exceeds 5% of the purchase price, the excess will be deducted from the property’s valuation, directly impacting how much money they will lend you.
Birmingham’s Strategic Development Zones
Birmingham City Council’s ongoing implementation of the Birmingham Local Plan has triggered massive residential target zones, creating rich pockets of new build stock. Where you choose to buy heavily influences the developer profile and the type of mortgage product that will fit best:
- The City Centre & Digbeth (B5 & B12): Driven heavily by major schemes like the £1.9 billion Smithfield redevelopment and the Beorma Quarter, this area is dominated by high-density, energy-efficient apartment blocks. Buyers here need lenders who are highly comfortable with high-rise apartment blocks and have flexible criteria regarding cladding and service charge ratios.
- The Jewellery Quarter & Hockley (B18): Regeneration projects such as Newhall Hill bring sleek, low-rise apartment schemes and townhouses into historic conservation areas. Mortgages here require careful valuation assessments to ensure the new build design respects the local architectural heritage restrictions.
- The Southern & Northern Suburbs (Edgbaston, Longbridge, Erdington): Major brownfield transformations, such as the former Tower Ballroom site at Edgbaston Reservoir or the West Longbridge masterplan, are introducing large-scale houses. These developments are prime territory for mainstream, competitive New Build Mortgages In Birmingham that support green mortgage incentives.
Crucial Lending Pitfalls: The Offer Validity Trap
The single biggest operational risk when purchasing an off-plan property in the West Midlands is the gap between your mortgage offer being issued and the actual completion date of the building.
A standard residential mortgage offer is usually valid for 3 to 6 months. However, construction timelines frequently slip due to material supply chains or local utility connections. If your mortgage offer expires before the developer hands over the keys, you will have to reapply. If your financial circumstances have changed or interest rates have fluctuated in the interim, you could find yourself exposed.
Critical Warning: Always look for lenders offering dedicated new build products that provide a guaranteed 9-to-12-month offer validity window, with the option to extend for a further 3 months if construction delays occur.
Local Regulations, Warranty Frameworks, and Building Safety
Lenders will not release funds for New Build Mortgages In Birmingham unless the property is backed by an approved structural warranty provider. The vast majority of mainstream UK lenders require coverage from recognised bodies such as the National House Building Council (NHBC), Premier Guarantee, or LABC Warranty.
Additionally, under the structural oversight of the Birmingham City Council Building Safety Team—which rigidly enforces the Building Safety Act—any building exceeding 18 metres or 7 storeys must maintain a flawless “Golden Thread” of digital safety documentation. Lenders now demand absolute clarity on these safety approvals before signing off on apartment mortgages in the city centre.
Comparison: New Build Mortgages vs Standard Residential Mortgages
| Feature | New Build Mortgages (Birmingham) | Standard Residential Mortgages |
| Typical Maximum LTV (Flats) | 80% – 85% LTV | Up to 95% LTV |
| Typical Maximum LTV (Houses) | 85% – 90% LTV | Up to 95% LTV |
| Offer Validity Period | 9 to 12 months (with extension options) | 3 to 6 months maximum |
| Required Documentation | Structural Warranty Certificate & Building Control Sign-off | Standard HomeBuyer Report or Building Survey |
| Energy Efficiency Perks | Highly eligible for lower-rate “Green Mortgages” (EPC A or B) | Rare; properties rarely meet strict modern green criteria |
Summary: Navigating Your Purchase Successfully
Timing is everything. Because developers usually demand an exchange of contracts within 28 days of reserving a plot, you cannot afford to wait for construction to finish before arranging your financing. Working with a specialist broker who understands the localized nuances of the Birmingham market is the most secure path to ensuring your mortgage offer stays aligned with your developer’s timeline.
Whether you need tailored advice on your next home purchase, remortgage, or specialist property finance, our local team is here to help. Speak with an expert at The Mortgage Hub today to explore your best whole-of-market options.
Call us: 0121 323 4999
Email us: mortgages@the-mortgage-hub.co.uk
References
- Deloitte LLP – Birmingham Crane Survey: Tracking Urban Residential and Build-to-Rent Completions.
- Birmingham City Council – The Birmingham Local Plan & Building Safety Team Enforcement Protocols.
- Glenigan Construction Data – West Midlands Residential Development Pipeline and Contractor Analysis.